Houston Mortgage Broker We give you the real number before you tour a single house.
Your payment, your price range, your cash to close, and the MUD tax nobody else quotes. Houston and Fort Bend buyers work with us because the process is predictable. You know what is coming, what it costs, and when it closes.
- We shop 35+ wholesale lenders for you. Not one bank's rate sheet.
- A real person calls you back. Usually within minutes.
- Before your offer goes in, we call the listing agent and confirm your approval is real. Most lenders never do this, and in a multiple offer it is often what wins the house.
- When rates drop, we refinance you at no lender cost.
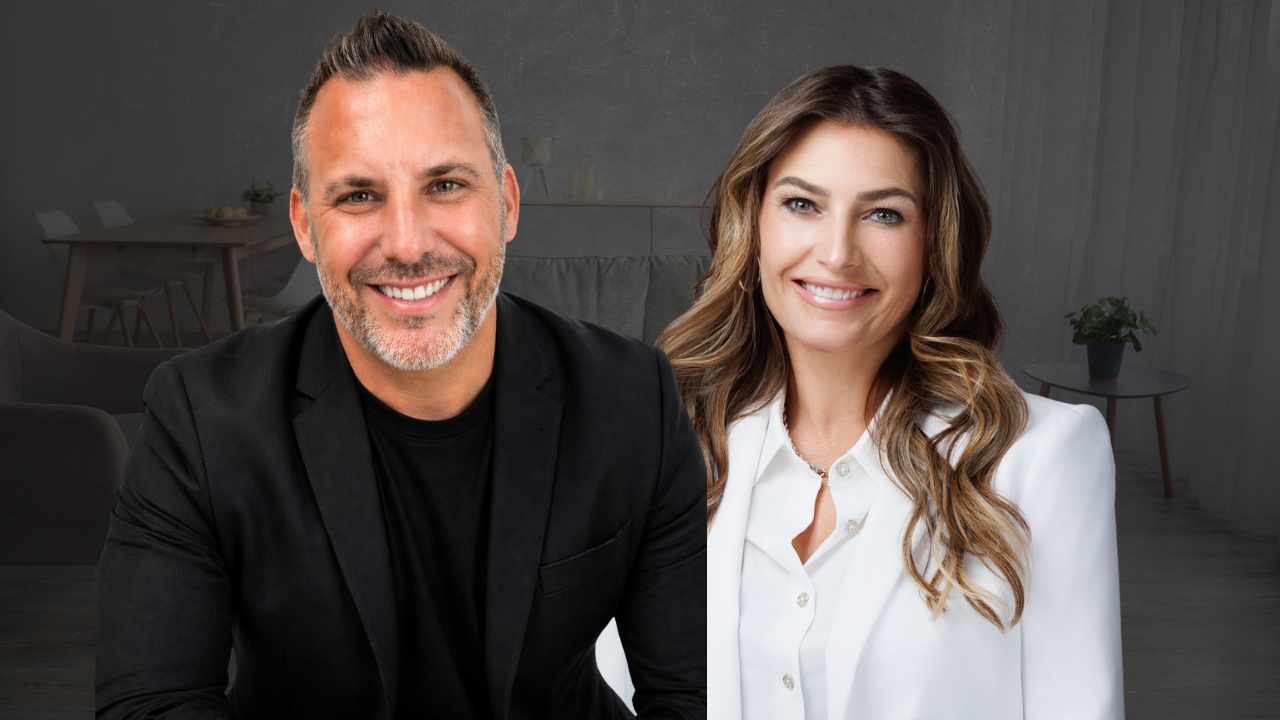
Steve and Stephanie Kyles, mortgage brokers serving Houston and Fort Bend County / NMLS #330894
Start your Clear Move Plan
Three questions. Then we call you and build the plan together. Sales price, monthly payment, cash to close.
No cost, no obligation, and no credit application to get your numbers.
Steve Kyles NMLS #330894
In the Houston mortgage business since 2002. Co-owner of ProLending Mortgage. Has financed homes in nearly every MUD district between Cypress and Galveston, which is why the calculator on this page knows what the others do not. Licensed in Texas.
Stephanie Kyles Loan Officer
Works every file alongside Steve. Between them you get two people who know your loan, which is the difference between calling a lender and calling the person who answers.
ProLending Mortgage, LLC / Company NMLS #262563 / Licensed by the Texas Department of Savings and Mortgage Lending / Equal Housing Opportunity. Rates shown anywhere on this site are examples, not quotes.
Run your own numbers
What would the payment actually be?
Move the numbers around until it feels right. This one runs real Harris, Fort Bend and Waller County tax rates, it knows what a MUD district does to your payment, and it prices mortgage insurance off the actual rate card instead of pretending it does not exist.
Best when your credit is 620 or higher. Mortgage insurance drops off at 20% equity.
Two borrowers prices the mortgage insurance lower, which most lenders never mention. Leave MUD on Yes if you are not sure, because most Houston-area new construction sits in one.
$19,250
An example rate, not a quote. Yours comes from the Clarity Call.
Starting estimate by price. Edit it if you have a real quote.
Estimated from your credit and down payment. If we have quoted you a real MI figure, type it here and everything recalculates.
MUD districts run higher. Edit this if you know the district's actual rate.
Estimated monthly payment
- Principal and interest$0
- Property taxes$0
- Homeowners insurance$0
- Mortgage insurance$0
- HOA$0
Estimates for planning only. Not a loan commitment, a rate lock, or an offer to extend credit. Actual payment and cash to close depend on your credit, the property, the final tax and insurance figures, and your loan terms. Rates change daily. Steve Kyles NMLS #330894, ProLending Mortgage NMLS #262563. Equal Housing Opportunity.
Mortgage insurance is estimated from what real files actually close at, not the published rate card, which is a list price most borrowers beat. Your actual factor depends on the mortgage insurance company, your credit, your debt ratio and the coverage level. PMI is charged on the original loan amount and cancels automatically at 78% of original value. Tax rates for Harris, Fort Bend and Waller counties come from the county tax offices and Katy ISD. Example rate is the Freddie Mac 30-year average for the week of September 3, 2026.
Why we built it this way
You should not feel like you are guessing. You should feel like you are deciding.
- Rates that change between the quote and the lock
- Fees that show up at the closing table
- Timelines that slide without warning
- Communication that goes silent for days
- Conditions that appear at the last minute
- A lender who disappears after closing
That is the mortgage most people have had. Ours takes all six off the table, and it runs the same way on every file we touch.
The question everyone asks first
How much do you need to make to buy a house in Houston?
Every national calculator answers this with an average property tax rate of about 1.1%. Houston is not 1.1%. Once you add a MUD district, plenty of Fort Bend and Harris County addresses land near 2.49%. That gap is why buyers get pre-approved online for a number they cannot actually close on. Here is the same math run with real Houston taxes.
| Home price | Monthly payment with taxes, insurance and MI | Income needed in Houston | What a national calculator tells you |
|---|---|---|---|
| $250,000 | $2,435 | $65,000 | $57,000 |
| $300,000 | $2,859 | $76,000 | $67,000 |
| $350,000 | $3,283 | $88,000 | $77,000 |
| $400,000 | $3,732 | $100,000 | $87,000 |
| $500,000 | $4,580 | $122,000 | $107,000 |
| $600,000 | $5,453 | $145,000 | $127,000 |
On a $400,000 house the national number is $87,000. The Houston number is $100,000.
That $13,000 gap is property tax. It is the most common reason a buyer gets approved online, writes an offer, and then finds out the payment does not work. Nobody lied to them. The calculator just did not know where they were buying.
Three things move these numbers in your favor, and every one of them is worth a conversation. Buying in a no-MUD neighborhood. Putting more down, which cuts both the loan and the mortgage insurance. And your credit score, because the difference between 700 and 760 changes the rate and the MI factor at the same time.
Run your own price in the calculator above, then call us. We will tell you the income and the credit it actually takes for the neighborhood you are looking at, before you talk to a single listing agent.
The number nobody quotes you
Two identical houses. A $588 a month difference.
A Municipal Utility District is a local government that borrowed money to build the water, sewer and drainage for a neighborhood. You repay those bonds through an extra line on your property tax bill. It is not in the listing, it is not in the builder's monthly payment estimate, and it is not in any national mortgage calculator. Here is what it does to the payment on a $500,000 home.
| Neighborhood | City | Total tax rate | Taxes per month on $500,000 |
|---|---|---|---|
| Pearland, outside the city limitsA Pearland mailing address that sits outside the city pays none of the $0.63 city rate. About $210 a month on a median home. | Pearland | 1.71% | $712 |
| Sugar CreekNo MUD and no levee district at all. Four taxing entities total. | Sugar Land | 1.8377% | $766 |
| In-city Rosenberg, no MUDLowest total rate in Fort Bend County. Rosenberg levies $0.30 where Richmond levies $0.63. | Rosenberg | 1.8689% | $779 |
| Weston LakesMUD 81 at $0.361, the lowest in Fulshear. The city itself levies no property tax. | Fulshear | 2.03% | $846 |
| GreatwoodNo MUD, but zoned to Lamar CISD instead of Fort Bend ISD, which runs nine cents higher. | Sugar Land | 2.13% | $888 |
| TelfairFour MUDs across the community. The community site publishes the sum of all four. No house pays all four. You pay one. | Sugar Land | 2.40% | $1,000 |
| Cross Creek RanchFive different MUDs from $0.68 to $1.30, and the community splits between Lamar CISD and Katy ISD. Two houses on one street can have different schools and different tax bills. | Fulshear | 2.51 to 3.13% | $1,046 to $1,304 |
| Harvest GreenThree separate MUDs. Three different tax bills inside one community. | Richmond | 2.72 to 2.93% | $1,133 to $1,221 |
| ImperialThe Imperial Redevelopment District at $0.97. The most expensive tax address in Sugar Land. | Sugar Land | 2.81% | $1,171 |
| Fulshear LakesA new district carrying bonds against very few finished homes. Most Fulshear MUDs also offer no homestead exemption. | Fulshear | 3.12% | $1,300 |
Same $500,000 house. Pearland outside the city limits pays $712 a month in taxes. Fulshear Lakes pays $1,300.
That is $588 a month, or $7,050 a year. It is often the difference between qualifying for the house and not qualifying for it.
Two things worth knowing before this scares you off a neighborhood. A high MUD rate usually comes down. Fort Bend MUD 173 went from $1.27 in 2020 to $0.87 in 2025, because a new district starts with bonds against very few homes and steps down as the neighborhood fills in. A high-MUD house is often priced lower to begin with, too. The mistake is not buying in a MUD. The mistake is finding out about it after your offer is accepted.
We pull the exact rate for your address before you write an offer. Not the community average. Not the builder's estimate. The rate on that parcel.
What working with us looks like
Five things happen on every file. Same way every time.
Five standards, in this order, on every file. Whether the market is calm or the market is a mess.
-
The Welcome Call™
Someone actually calls you back. We answer your first questions, get you started, and put the next call on the calendar.
Usually within minutes -
The Clarity Call™
Thirty minutes on the phone where we build your Clear Move Plan. Your sales price, your monthly payment, your cash to close. Every question answered before you hang up.
Scheduled around you -
The Predictable Payment™
One page with your full payment, principal, interest, taxes, insurance, and any HOA, plus what you need at the closing table. In your hands before you start touring homes.
Before you shop -
The Predictable Close Calendar™
Every milestone from contract to keys, with a date on it. You and your agent both know what happens next, so nobody has to chase an update.
Within 24 hours of contract -
The Predictable Annual Review™
Every year, on the anniversary of your closing, we call. Where rates are, whether a refinance makes sense for you, and what your equity could do. Closing is where the relationship starts paying you back.
Every year, for as long as you own the home
In their words
What Houston families say after they close.
What this saves you
Two things that put real money back in your pocket.
Most lenders compete on a rate they quote you once. We compete on what you actually pay, on day one and every year after.
The ProLending Advantage™
We are not a bank with one set of rates and one set of rules. We hold relationships with more than 35 wholesale lenders, and we take your file to the ones that fit your situation. Self-employed, commission income, a credit event a few years back, a tight closing window. Somebody out there prices that well, and finding them is our job, not yours.
"Most people think they're shopping, but they're really just comparing. We actually shop the market for you."
"We do not work for a bank. We work for you."
The Sure-Fi Advantage™
Buy your home with us, and when rates come down, we refinance you with no lender cost. Not a discount. Not a coupon with a deadline. The lender fees come off, every time, for as long as you have the loan.
- Underwriting fee$999 waived
- Processing fee$995 waived
- Credit report fee$250 waived
- Total lender cost savings$2,244
Third-party costs such as appraisal and title are set by outside companies and are not controlled by any lender, so those are not included in the waiver. You pay only those minimal third-party costs when the time comes.
The money most Houston buyers leave on the table
Houston down payment assistance, and the catch nobody mentions.
There is real money available in this city. There is also a requirement buried in it that stops most people before they start.
What is actually out there
The City of Houston's Homebuyer Assistance Program offers up to $75,000 based on demonstrated need, for buyers at or below 80% of area median income, buying inside the city limits. Statewide, TSAHC and TDHCA offer down payment help that works across the metro, and an MCC tax credit can cut your federal tax bill every year you own the home.
Harvey-affected buyers may qualify for a separate program worth considerably more.
Funding moves. Programs open and close. The City of Houston program has been paused before and will be again, so the answer to whether it is open is always today's answer, not last year's.
Here is the catch
Nearly every one of these programs requires you to bring a lender pre-approval letter dated within the last 120 days before you can apply. Several also require an eight-hour HUD-approved homebuyer education certificate.
So the order matters. People find the program first, get excited, and then discover they cannot apply until a lender has already run their file. By the time they circle back, the funding round is closed.
Get the pre-approval first. Then apply. It costs you nothing and it is the only sequence that works.
Which loan fits you
Every loan program, explained without the jargon.
FHA Loans
3.5% down, built for lower credit scores. Mortgage insurance stays for the life of most FHA loans, which matters more than people think.
Conventional Loans
3% down is possible. Mortgage insurance comes off at 20% equity, and strong credit prices it low.
VA Loans
Zero down, no monthly mortgage insurance, and the best terms in the market if you have served.
USDA Loans
Zero down in qualifying areas. Parts of Waller and Fort Bend County still qualify and almost nobody checks.
Down Payment Assistance
City of Houston, TSAHC, TDHCA and MCC. Most of these require a lender pre-approval before you can even apply.
First-Time Buyers
What you actually need, what you do not, and which program fits. Written for Houston, not a national average.
Self-Employed
Write-offs make your income look smaller than it is. There are programs built for that and most lenders never mention them.
Bank Statement Loans
Qualify on deposits instead of tax returns. Built for business owners and commission income.
DSCR and Investor Loans
Qualify on the property's rent rather than your personal income. No tax returns.
Jumbo Loans
Above the conforming limit. Different guidelines, different pricing, and a lot more room to shop.
New Construction
You do not have to use the builder's lender. We will run their incentive against ours and tell you honestly which wins.
Pre-Approval
What lenders actually look at, and what makes an approval strong enough to win a competitive offer.
Straight answers
The questions Houston buyers actually ask us.
If yours is not here, call or text. We would rather answer it now than have you guess at it.
Still have a question?
Ask it out loud. Most of what people worry about takes about four minutes to clear up.
Call or text 832-449-2915How much do I need for a down payment in Houston?
What credit score do I need to buy a house?
What is the difference between FHA and conventional?
Why is my property tax bill so high in Texas?
Are there down payment assistance programs in Texas?
How fast can I get pre-approved?
Do you charge lender fees?
Why use a broker instead of my bank?
Do I have to use the builder's preferred lender?
What is a MUD tax and how does it change what I qualify for?
How does flood insurance affect my mortgage approval?
When does mortgage insurance come off?
What does the homestead exemption do, and when do I file?
How much house can I afford in Houston?
How much are closing costs in Houston?
How long does it take to close on a house in Houston?
Can I get a mortgage if I am self-employed or paid on commission?
What areas do you serve?
One call is all it takes
Let's build your Clear Move Plan.
Thirty minutes with a Houston mortgage broker who works for you. You will hang up knowing your price range, your monthly payment, and exactly what you need at closing.